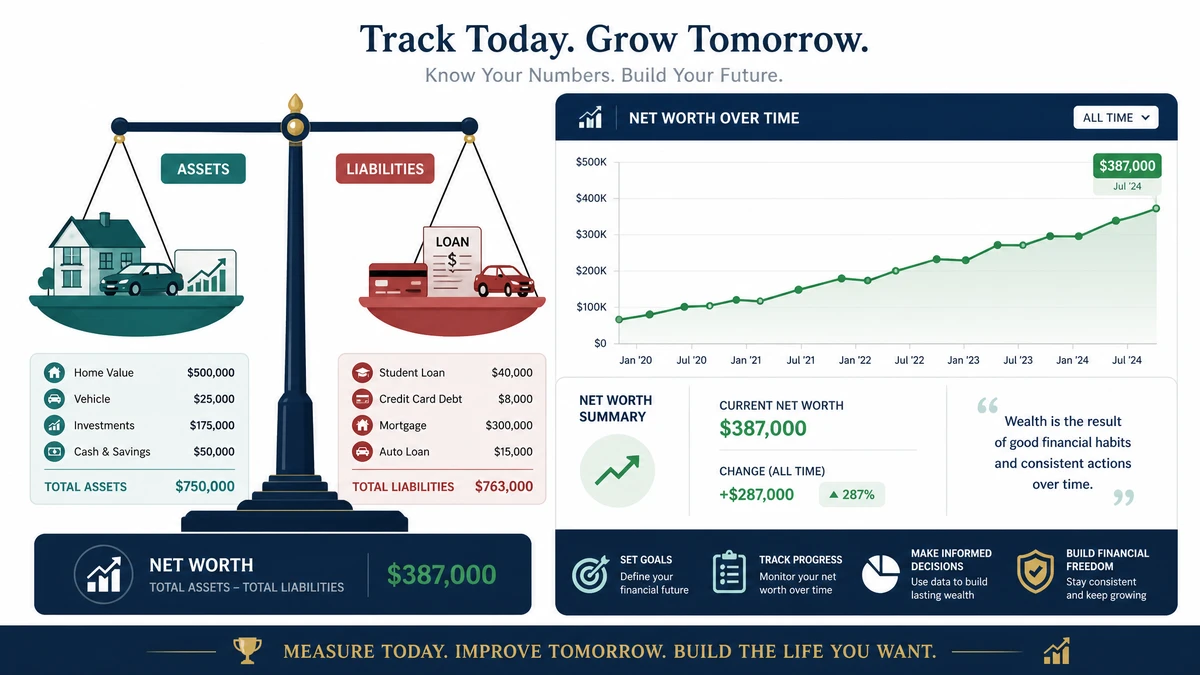
How to Track Your Net Worth and Actually Grow It
Your income tells you how much money flows in, but your net worth tells you whether you're actually getting ahead. It's the single most honest measure of your financial health, and the good news is that tracking it is simple once you know how. This guide walks you through how to track your net worth step by step, what moves the number, and how to grow it steadily over time.
What Is Net Worth and Why Does It Matter?
Quick answer: Net worth is everything you own (your assets) minus everything you owe (your liabilities). If your assets total $50,000 and your debts total $20,000, your net worth is $30,000.
Net worth matters because it captures your whole financial picture in one number, something a bank balance can never do. Your checking account might look healthy right after payday and empty right before it, but that swing tells you nothing about your progress. Net worth, tracked over time, reveals whether you're genuinely building wealth or just treading water.
Here's a sobering reality check: according to the Federal Reserve, the median net worth of U.S. households in 2022 was $192,700, yet most people have no idea what their own number is. Simply knowing yours puts you ahead of the majority and gives you a clear baseline to improve from.
How Do You Calculate Your Net Worth?
Net Worth Formula:
Net Worth = Total Assets − Total Liabilities
Calculating your net worth is refreshingly straightforward. You add up the value of everything you own, add up everything you owe, and subtract the second number from the first. The result can be positive or negative, and either way it's a useful starting point. Before you crunch the math, it helps to list everything out so nothing gets missed.
What Counts as an Asset?
Assets are anything you own that has real monetary value. Be thorough and honest with your estimates. Common assets include:
- Cash and checking accounts you can access right now.
- Savings and high-yield savings accounts, including your emergency fund.
- Investments such as brokerage accounts, stocks, bonds, and index funds.
- Retirement accounts like a 401(k), IRA, or pension.
- Real estate, valued at what your home would realistically sell for today.
- Valuables such as a paid-off car, jewelry, or other items worth a meaningful amount.
What Counts as a Liability?
Liabilities are everything you owe. List them all out before doing the math so your number is accurate. Typical liabilities include:
- Mortgage balance on your home.
- Car loans still being paid off.
- Student loans from your education.
- Credit card debt carried month to month.
- Personal loans and any other outstanding balances.
Once you have both totals, subtract your liabilities from your assets. To make this effortless and repeatable, our investment and net worth calculator tracker does the math for you and keeps a running history so you can watch your number change over time.
How Often Should You Track Your Net Worth?
For most people, updating your net worth once a month strikes the perfect balance. Monthly tracking is frequent enough to keep you engaged and accountable, but not so frequent that normal market swings make you anxious. Pick a consistent day, like the first of the month, and make it a quick routine.
If monthly feels like too much, quarterly still works well and smooths out short-term noise. The most important thing is consistency: tracking the same way at regular intervals is what turns a single snapshot into a meaningful trend you can actually learn from.
What Actually Moves Your Net Worth?
Your net worth changes for two basic reasons: your assets grow or shrink, and your debts rise or fall. Understanding these levers helps you focus your energy where it counts.
- Paying down debt instantly increases your net worth by shrinking the liabilities side of the equation.
- Saving and investing adds to your assets, and over time compound growth does much of the heavy lifting.
- Market performance moves the value of your investments and retirement accounts up and down.
- Home value changes can nudge your number, though your home's worth is only an estimate until you sell.
- Big purchases and lifestyle inflation can quietly stall your progress if spending rises to match your income.
Because both saving and debt payoff move the needle, your personal savings rate is one of the strongest predictors of how fast your net worth will climb.
The Best Tools to Track and Grow Your Net Worth
You don't need expensive software to track your net worth well. A few simple tools do the job beautifully.
A Dedicated Net Worth Tracker
A structured tracker beats scattered notes every time because it keeps all your accounts in one place and shows the trend at a glance. Our guide to the net worth tracker spreadsheet explains how to set one up so updating your number takes just minutes each month.
Free Calculators for Planning Ahead
Calculators help you see where your habits are heading. An investment growth calculator shows how consistent contributions can compound into serious wealth, while a budget calculator helps you free up the cash to fund those contributions in the first place.
How to Grow Your Net Worth Over Time
Growing your net worth comes down to two moves: increasing your assets and reducing your liabilities. Do both consistently and the number takes care of itself.
Increase Your Assets
Automate your saving and investing so money grows before you can spend it. Contribute enough to capture any employer retirement match, invest regularly through market ups and downs, and let compound growth work over years, not weeks. Building a solid emergency fund also protects your assets by keeping you from selling investments or taking on debt when surprises strike.
Reduce Your Liabilities
Attack high-interest debt first, since every dollar of credit card balance you eliminate is a guaranteed boost to your net worth. Avoid taking on new debt for depreciating purchases, and resist letting your spending climb every time your income does. Keeping lifestyle inflation in check is one of the most underrated wealth-building habits there is.
Common Net Worth Tracking Mistakes to Avoid
A few simple errors can distort your number or discourage you unnecessarily. Watch out for these:
- Overvaluing your assets, especially your home or car. Use realistic resale values, not wishful thinking.
- Forgetting to include debts, which makes your number look better than it really is.
- Panicking over short-term dips caused by normal market swings instead of focusing on the long-term trend.
- Tracking inconsistently, which makes it impossible to see real progress.
- Comparing yourself to others instead of competing with your own past number.
Is a Negative Net Worth a Problem?
A negative net worth is common and usually temporary, especially early in adulthood. If you have student loans, a new mortgage, or a car loan, your debts may outweigh your assets for a while, and that's normal. What matters is the direction of travel, not the starting point.
The moment you start tracking, you can watch that number climb as you pay down debt and build assets. Many people move from negative to positive net worth faster than they expect once they have a clear plan and a tool to measure progress. The trend is what tells the real story.
Frequently Asked Questions
What is a good net worth?
There's no single "good" number, because it depends heavily on your age, income, and stage of life. A helpful benchmark is the median U.S. household net worth of $192,700 reported by the Federal Reserve for 2022, but the most useful comparison is your own past number. If your net worth is trending upward year over year, you're doing well regardless of how you stack up against averages.
How do I calculate my net worth?
Add up the value of everything you own, including cash, savings, investments, retirement accounts, and real estate, to get your total assets. Then add up everything you owe, such as your mortgage, car loans, student loans, and credit card debt, to get your total liabilities. Subtract your liabilities from your assets, and the result is your net worth. A net worth tracker or calculator can do this math automatically.
How often should I check my net worth?
Once a month works well for most people. It's frequent enough to keep you engaged and spot trends, but not so often that everyday market fluctuations cause stress. If monthly feels like too much, quarterly is a fine alternative. The key is to track at consistent intervals so you can see a genuine trend rather than random snapshots.
Should I include my home in my net worth?
Yes, your home is typically your largest asset, so it belongs in the calculation. Use a realistic estimate of what it would sell for today, and remember to list your remaining mortgage balance as a liability. Because a home isn't easily converted to cash, some people also track a "liquid net worth" that excludes property to see how much they could access quickly if needed.
What's the difference between net worth and income?
Income is the money that flows in over a period of time, like your salary or side earnings, while net worth is a snapshot of your total wealth at a single moment. A high income doesn't automatically mean a high net worth; someone who earns a lot but spends it all can have a lower net worth than a modest earner who saves consistently. Net worth measures what you keep, not just what you make.
Can I grow my net worth while paying off debt?
Definitely. Every debt payment reduces your liabilities, which directly increases your net worth. Many people grow their net worth fastest during their debt-payoff years because each payment delivers a guaranteed return. If you can save even a small amount while paying down debt, you'll build assets and shrink liabilities at the same time, moving your number up from both directions.
Why is tracking net worth better than checking my bank balance?
Your bank balance only shows the cash in one account at one moment, which swings dramatically between paydays and bills. Net worth captures your entire financial position, including investments, retirement accounts, and debts. Tracking it over time reveals whether you're truly building wealth, something a bank balance simply can't tell you. It's the difference between a single frame and the whole movie.
The Bottom Line
Tracking your net worth is the clearest way to know whether your money habits are actually working. Add up what you own, subtract what you owe, and revisit the number every month. Then focus on the two levers that grow it: building assets and shrinking debt. Ready to find your number and watch it climb? Start with our investment and net worth calculator tracker and set your first baseline today.